When One Future Isn’t Enough

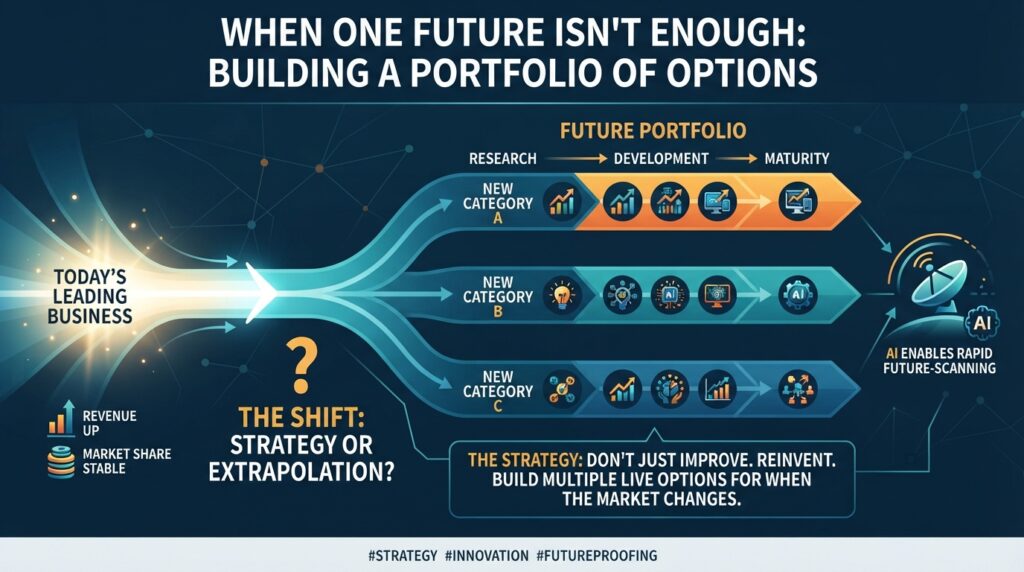
Your company is winning. Revenue is up, market share is stable, and the board likes what it sees. But look past the numbers and a real question is waiting: is this a strategy, or just an extrapolation of what’s worked so far?

That distinction matters more than it sounds like it should. Extrapolation works fine right up until the market shifts. By then, it’s too late to build an alternative.

Take Kodak and Fujifilm. Both companies had digital photography technology decades before it upended their industry. Kodak’s version of the story gets told the most: brilliant engineers, a dominant brand, and a board that shelved the innovation rather than risk film sales. When digital cameras finally took over, Kodak had no second act ready.

Fujifilm had the same technology and the same warning signs. Its leadership drew a different conclusion: photographic film would not pay the bills forever. So it went looking through its own laboratories for technologies that could become something else entirely. Two bets came out of that search, developed side by side. One was Instax, an instant-camera category built on Fujifilm’s imaging chemistry. The other was Astalift, a cosmetics line built on collagen and nanotechnology the company had originally developed for film. Neither was a better camera. Both answered a customer question film photography never asked.

That’s the real lesson. Improving a product and reinventing a category are not the same move. One extends an answer. The other asks a new question.

Kodak’s failure has company. Blockbuster stayed anchored to the physical rental store while Netflix built a fundamentally different way to watch movies, and filed for bankruptcy in 2010. Nokia kept optimizing handsets while Apple and Google moved the competition to software and app ecosystems, and eventually sold its phone business to Microsoft. Borders kept investing in the physical bookstore, outsourced its own online sales to Amazon in 2001, and liquidated a decade later.

Look closely at those three and you’ll notice they didn’t fail the way Kodak did. Kodak’s category disappeared: film photography became structurally unattractive, and there was nothing to pivot back into. Blockbuster, Nokia, and Borders had it worse in one sense. The underlying customer need never went away — people still wanted to watch movies, communicate on the go, and read books. What disappeared was their claim on it, because somebody else built a new category to serve that same need. A strong core business can keep performing right up to the moment a competitor creates the category that makes it irrelevant.

That’s what makes a portfolio of candidate futures worth the trouble. Amazon didn’t wait for online retail to plateau before placing its next bet. It launched S3 in 2006 and EC2 not long after, building the cloud-computing category while its retail business was still scaling. Alphabet does something similar on purpose: it runs a set of “Other Bets” — Waymo, Verily, and several others — deliberately kept at different stages of development, some barely past the research stage, so the company always has more than one shot at the future in play at once.

None of this is really new. IBM ran something similar in the early 2000s under a formal program that tracked what it called emerging business opportunities. Within three years, the portfolio had grown to seventeen candidates, spanning life sciences, Linux, pervasive computing, and business-process integration, each one tracked against its own milestones rather than forced through the existing business’s metrics.

Samsung did something comparable in 2010, naming five future growth businesses — including solar cells, batteries, and biopharmaceuticals — and committing serious capital to develop them in parallel. Some of the five went nowhere. A few became genuinely important. That’s not a coincidence, and it’s not a weakness in the approach. It’s the approach working as intended: the value isn’t in a high hit rate, it’s in having more than one live option when the environment shifts.

Naming that pattern is the easy part. Committing real resources to a future that might not happen is much harder, especially while the current category is still paying the bills. Few leadership teams even attempt to plan fifteen or thirty years out. Fewer still try to hold multiple long-range futures at the same time.

Until recently, that kind of work belonged to consultants and academics, who produced dense reports that ended up on a shelf. AI changes what’s possible now. It took the launch of ChatGPT to reveal what GPT-3 had only hinted at a year earlier, and most organizations planning long-term in 2021 missed that shift entirely, because nobody was scanning for it. Tools like Preempt.live can now surface thousands of plausible futures for an industry in an afternoon, which lowers the cost of asking “what else might happen” close to zero.

If your organization already has a few candidate categories in mind, the next steps aren’t complicated:

  1. Name a handful of candidate categories, with input from AI and your board.
  2. Assign each one to a champion who wants to see it succeed, not a department that inherits it as a side project.
  3. Teach each champion to use AI to track the faint signals that would tell you a candidate is starting to matter.

None of this requires certainty. It requires candidates, champions, and the discipline to keep watching for the next fifteen to thirty years.

Your current strategy is paying the bills today. Start building the one that will pay them next.

[This article is a longer, AI-generated version of an original Gleaner column.]

P.S. — Five prompts to run through your own AI tool

1. “List every product or service my organization sells today. For each one, tell me: if this disappeared entirely in the next ten years, would our underlying customer need disappear with it, or would someone else just be serving that need in a different way?”

2. “Based on what you know about my industry, name five to ten emerging categories that don’t exist yet but plausibly could within the next 15 years. Don’t filter for feasibility — I want the raw list first.”

3. “Play devil’s advocate: what is the single strongest argument that my current category will keep paying the bills for the next 15 years, with no need for a backup? Then tell me what would have to be true for that argument to be wrong.”

4. “If I had to hand one candidate future to a named person on my team — not a department — and ask them to genuinely champion it, who on my team already has the curiosity or skills to do that well, based on what I tell you about them?”

5. “Help me design a simple, low-effort way to monitor faint signals for [insert one candidate category]. What sources, search terms, or data points should someone check monthly to catch early movement?”
Unlocking the Power of Irresistible Offers

Many companies lack a formal product development unit. Instead, ideas are casually pitched to the CEO, and the next steps depend on their mood at the moment. This approach often falls short in delivering consistent innovation, resulting in products and services that closely resemble competitors’ offerings. If you’re a monopoly, your products might become stale over time. To stand out, you need innovative ideas that provide real value to your customers.

The challenge? You may not have the resources to hire a full-time R&D team, and even if you could, you might not trust newcomers to handle the job effectively. So, how can you consistently set your offerings apart from the rest?

Recently, I experimented with an approach outlined by Alex Hormozi in his book, “$100m Offers.” This approach revolves around the customer experience and has yielded promising results. I highly recommend this method, as it takes an inside-out perspective. Let me walk you through the steps I followed, using a local example.

Step 1 – Envision Dream Outcomes

Start by listing the experiences you want your ideal customers to have. Even if some of these experiences seem unattainable, record them. The goal is to capture what your customers truly desire.

Step 2 – Identify Customer Pain Points

Think about the moment a customer considers your offering. What are the hurdles and obstacles preventing them from achieving their desired outcomes? Consider issues that arise during and after using your product or service. For instance, let’s imagine you own the Krispy Kreme franchise in Jamaica. If someone has never tried your donuts, what challenges might they face?

  • Traffic around the store’s location is congested.
  • There are long lines inside.
  • The customer is on a diet.
  • They don’t like overly sweet food.
  • They had a bad experience with a competitor’s product.

This is just a starting point. Keep going until you’ve identified at least a hundred pain points for your offering. The more you list, the deeper you’ll delve into the customer experience, leading to more valuable insights than traditional surveys.

Step 3 – Propose Solutions for Each Problem

Address each pain point with a solution, expressed in the form of a “How to…” statement. For example, “I am on a diet” could be solved with “How to enjoy our product while sticking to your diet.”

But don’t stop there. Be thorough.

Step 4 – Design Strategies to Implement Solutions

Let your imagination run free in this step. Create offers, or “vehicles,” that correspond to each “How to…” solution from the previous step. Give these vehicles catchy, descriptive names that would grab your customer’s attention. Be comprehensive and include even those you may not intend to provide.

For example, considering the solution “How to enjoy our product while on a diet,” what could you name the corresponding vehicles to attract customers?

  • The 47-Calorie Donut Hole
  • The Perfect Donut for a Dieter’s Cheat Day (Help dieters plan effective cheat days with this brand.)
  • Free Traffic Morsels (Offer complimentary pastries for people stuck in traffic.)
  • Our Lowest-Ever Calorie/Fat Gram Donut (Give diet-conscious customers a guilt-free treat.)
  • The Unsweet Spicy Donut (Appealing to dieters who prefer savory over sweet.)

This list took me just 10 minutes to create. You don’t need to be exceptionally creative; following this structured process can help you brainstorm at an impressive pace.

Step 5 – Evaluate and Prioritize Solutions

Assign two measures to each vehicle: its value to the customer and the cost to your business to offer it. Use these measures to rank your offers and establish a timeline for implementation.

In conclusion, these lists can jumpstart your innovation. Thanks to Alex Hormozi, these lightweight forms of R&D leverage the everyday experiences you’re already gathering.

This article appeared in an earlier form as a Jamaica Gleaner column.

How to create and dominate business categories

In your company’s strategic planning activities, you hope to make more than incremental improvements. Instead, your team dreams of brilliant decisions and breakthrough results. But are these a matter of luck? While fortune plays a role, Digicel’s introduction to the mobile telephony market is an example of a new competency: “category design.”

Christopher Lochhead would be proud of Digicel. He belongs to a cohort of content creators who call themselves the “Category Pirates.”

Responsible for several best-selling books, they argue that companies should not compete with other firms in existing categories. Instead, they should create and dominate brand new ones.

While this is far easier said than done, consider the example of Digicel.

Back in early 2001, cell phones in Jamaica were reserved for the privileged few. One would drop off a handset at a Cable and Wireless office for a few days, weeks, or months. The duration was unpredictable, and you needed to visit the building to see if the job was done.

You couldn’t help but notice employees who appeared annoyed at the intrusion. To the company, this was a minor operation…a nuisance. Many believed the local demand for this service was tiny. As a result, cell-phone signals were sporadic, perhaps offered in just enough locations to keep customers from complaining too much.

Looking back, it may seem that Digicel’s subsequent capture of 70% market share showed the power of competition. However, the company was actually doing something else your organization should consider: crafting a new category of service where no competitor existed. Here’s how they did it in spite of considerable risk.

1) New Technology

If Digicel were just another adversary, it would have used the same TDMA/CDMA technology C&W was using. Instead, it made a big bet on an approach Jamaicans had never seen: SIM-based, GSM.

To sign up, people would not only have to buy a phone but also a chip. Consequently, there were more moving parts. With the island’s low literacy rate, some believed people could not manage the sequence of actions required.

2) Island-Wide Coverage

If Digicel were merely competing with C&W, it would have fought to steal away high-value corporate and individual accounts in Upper St. Andrew. After all, they were existing users who could afford another monthly bill.

Instead, Digicel defined a new market. It offered service to some 75%+ of Jamaicans, only excluding the handful in the most remote locations.

This was a revolutionary strategy, and there was no guarantee it would work. Could ordinary people cover the added expense? Would they travel to a store (sometimes far away) to purchase a SIM card? How many were willing to learn how to use this new technology?

3) Customer Non-Care

C&W was well known for the poor service it offered to Caribbean customers. As a former part of the government, it appeared to be staffed with the worst of the former civil servants.

Digicel promised to offer a level of face-to-face service that was unprecedented. In the early days, it clearly delivered a stunning degree of customer care. Also, it undertook reward programs and prizes that gamified the business of mobile telephony for the first time. For several years, they offered cars as gifts for lucky customers during their annual Christmas promotions.

In retrospect, these three moves may seem to be obvious. But back then, it was a huge risk because each one relied on the other. Assumptions were made which could only be proven on launch day.

Yet, it still worked. Other islands in the region were envious as Jamaica rid itself of an unwanted monopoly…within days.

But this was no incremental improvement over C&W’s service…like yet another copycat pan chicken stand on Red Hills Road. It was a radical new strategy that combined fresh elements which had never been introduced to the Caribbean at scale.

Note that we Jamaicans love to “follow-fashion” each other, favoring the apparent safety of large numbers. It drove us to Olint and Cash Plus. Today it’s driving us to build high-end apartments on every available open lot.

It takes courage to bring about a new future, using only imagination and vision. But the good news is that this capability isn’t unique. This power is available to your organization.

But first you must understand that the essence of a breakthrough strategy is not duplication. Or competition. It’s “difference making” in which leaders define a new category in order to unlock fresh value.

Digicel did it, and so can your company in its next strategic planning session. I don’t intend to imply that doing so is easy. But there are proven methods for giving your creativity free rein that could lead to outstanding results.

This article was originally published in the Jamaica Gleaner.